This week I'm in Orlando for Fincon, the annual gathering of folks who work at the intersection of money and media. As a result, I haven't had time to do all of the things I normally do during a week. I haven't been reading or writing about money. Instead, I've done a lot of chatting with colleagues.
We've been coming together at Fincon since 2011. At first, we were nearly all strangers to each other. Today, many of these people are my closest friends — but they're friends I see in person only once or twice each year. I value every moment I get to spend with them.
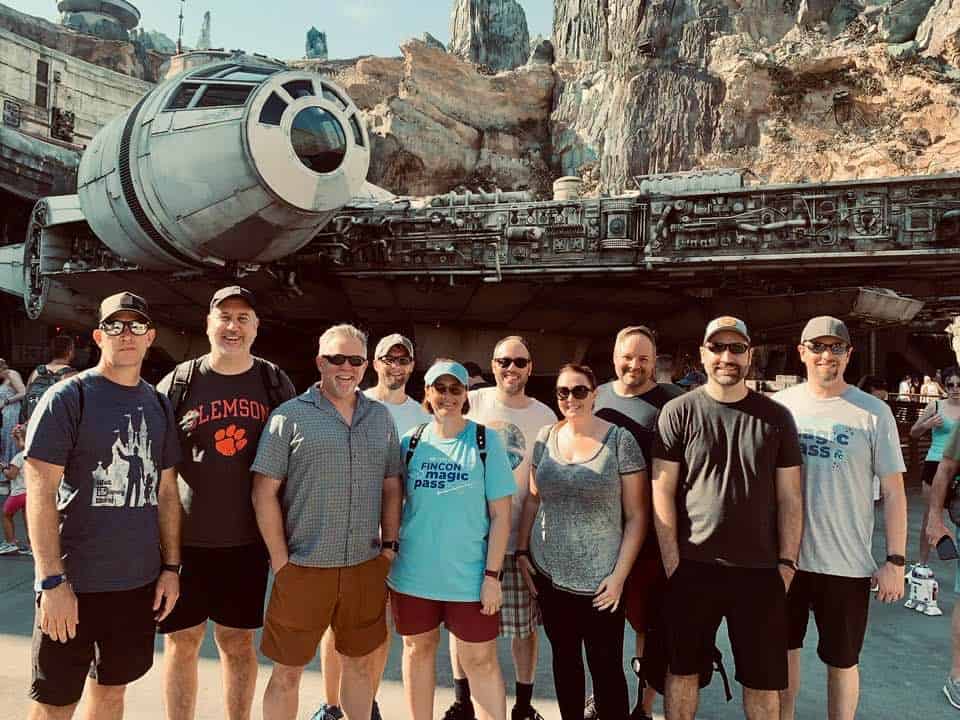
On Tuesday, for instance, a group of us booked a private VIP tour through the Disney theme parks. We had a blast. I mean, look at this wretched hive of scum and villainy…
Chatting with other money nerds this week has given me additional clarity about the future direction of Get Rich Slowly — on the web, on YouTube, and in the email newsletter.
You see, most money bloggers (and podcasters and YouTube creators) are in it for the money. That's fine. I have no problem with that. But that's not me.
Yes, I would very much like to earn income from the work that I do, but I'm in the fortunate position that I don't need to earn that income today. I had a windfall from the site thirteen years ago, which allows me to pursue this as a passion project (at least for a time).
Instead, I can focus on making Get Rich Slowly meaningful to me and useful to you. I can ignore the financial side of things while I work to build a resource that helps people master their money — and their lives. While I might not earn anything from the site today (or next week or even next year), I have faith that if I provide value, then eventually I'll discover a way to make money in a way that doesn't compromise my values.
Send Me Your Questions and Stories!
Anyhow, as part of my renewed vision for Get Rich Slowly, I want to interact more with you. I've been brainstorming a variety of ways to do this. Back when I started the site, for instance, GRS had two regular features that highlighted the community of readers.
First, there was an ongoing “Ask the Readers” column in which real-world readers presented questions and dilemmas for discussion. This was an opportunity for folks to seek advice from the community at large. Here are some actual past questions:
- Ask the Readers: How do I motivate my boyfriend to save money?
- Ask the readers: How can we afford to buy a house?
- Ask the Readers: Where's the fun in personal finance?
Second, there was a regular “Reader Stories” column in which people like you shared financial anecdotes from their lives. These stories were often tales of success but could also be interesting how-to articles. Here are a few past reader stories:
- “Reader Story: I quit my passion and took a boring job.”
- Reader Story: I fought the law (and the law won).
- Reader Story: Sailing away from the American Dream.
I'd like to bring these features back. Perhaps they won't be weekly as they used to. Maybe they'll only be monthly. It doesn't matter. What's important here is that it's an opportunity for Get Rich Slowly to be about more than just me. It's a chance for the site to help everyone get better with money.
To that end: If you have a financial question or money dilemma that you'd like help with, drop me a line. I'll work with you to craft a question for the GRS community. Similarly, if you have a money story you feel like sharing with everyone, send it in.
How to Submit a Story or Question
If you would like to share your story, or if you’d like to ask a question, please keep these guidelines in mind:
- Your story doesn’t have to be an example of what to do right with money, but be aware that other readers can get cranky with folks they think are making dumb decisions. If you think you can handle negative comments, then go ahead and share examples of what not to do.
- Keep things entertaining! Write naturally, as if you were sending an e-mail to a friend. Don’t try to gussy it up for Get Rich Slowly. I’ll help edit things so they’re presentable.
- People don't like bankruptcy and “I ran away from debt” stories. Your story can still have these elements, but try not to make them the focus. If your story is, “I got out of debt by declaring bankruptcy”, it’ll go near the bottom of the stack.
- Length doesn’t matter (your story can be long or short). You don’t have to put the story in MS Word or any other format. Just type it up and send it over to jdroth@getrichslowly (dot-org, not dot-com).
- If you need to be anonymous for whatever reason, be sure to specify that. Also, I'm happy to link to your website, but I will not run questions or stories that are blatant ploys at self-promotion. If what you send me is clearly meant to be an ad, you're just going to piss me off. It won't get published and I probably won't even reply.
So, please: Send me your stories and questions. I look forward to reading them, and to sharing the best with your fellow GRS readers.
from Get Rich Slowly https://ift.tt/r9NQ2Iz
Comments
Post a Comment
We will appreciate it, if you leave a comment.